ServicesUSDA Loans
USDA Loans in Leander, TX
A USDA loan can let you buy with no down payment when the property sits in an eligible area and your income falls under the local limit. We check both before you fall for a listing, then compare USDA with your other loan options so you pick the right fit.
What a USDA loan is and who it suits
USDA guaranteed loans are backed by the U.S. Department of Agriculture to help moderate-income buyers purchase in rural and edge-of-town areas. That government guarantee lets lenders offer full financing, so the down payment can be zero. You still need money for closing costs, though sellers can sometimes contribute toward them.
The trade-off is two tests most programs don't have. The address has to be in an eligible area, and the combined income of everyone who will live there has to fall under the limit for the county and family size. The property must be your primary residence, not a rental or a second place.
Around Leander, eligibility can change from one subdivision to the next, so we look up the exact address. We've spent 11 years in the mortgage industry explaining rules like these, and we lay USDA out beside FHA and conventional loans so you can see what each one costs you over time.
What we take care of on your USDA loan
- Property location lookup
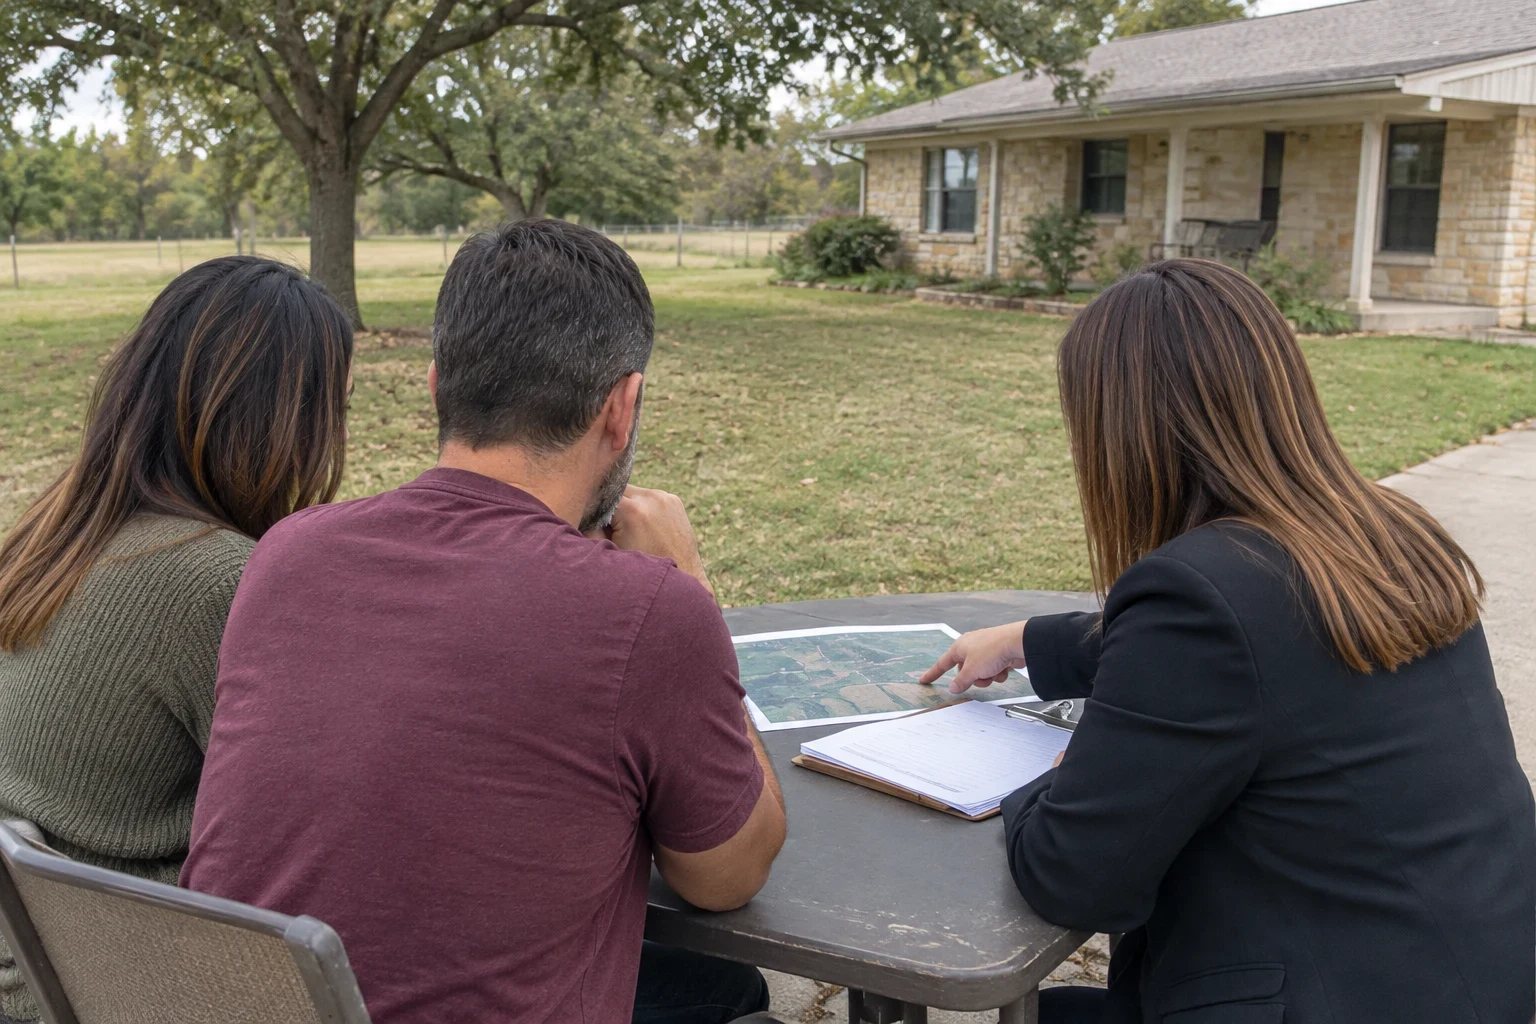
- Send us the listing you have in mind and we'll look it up on the USDA eligibility map while you're still deciding. A place that falls just past the boundary is better discovered on day one than after the appraisal comes back.
- Income limit math
- The program adds up income from every adult who will live in the property, including people who won't sign the loan. We work through it the way USDA does, taking allowed deductions for dependent children, childcare and certain medical costs, and then show you how close you are to the limit.
- USDA next to FHA and conventional
- We price a USDA loan alongside an FHA loan and a low-down-payment conventional loan. The USDA annual fee lasts as long as the loan, while conventional mortgage insurance can be removed down the road. Your credit and how long you expect to stay decide which one comes out ahead.
- Pre-qualification, then the full application
- It starts with a pre-qualification over the phone. When you're ready to move forward, we take the complete loan application by phone, by video or at our office.
- Following the file through USDA
- Once our underwriter signs off, the file goes to USDA for a second approval. We keep tabs on where it sits and call you as it moves, so the closing date you planned on stays within reach.
Signs a USDA loan may be right for you
Steady income, little saved
You can handle a monthly payment, but saving a large down payment would take years. USDA lets you buy now and keep your savings for closing costs and moving.
You're shopping past the city center
Newer subdivisions and acreage toward Liberty Hill or Jonestown are the kind of places worth checking. Only the map can confirm a specific address, so we look each one up.
Your income is moderate for the area
The limits are set by county and family size, and they're higher than many buyers expect. A quick review shows if you fall under the line.
You plan to live there full time
USDA is for a primary residence only. If you're buying to rent out or flip, our Conventional Loans or Hard Money Loans pages are a better starting point.
Fair credit, not perfect
USDA doesn't require a spotless record. A steady payment history over the past year carries real weight, and we'll talk through what underwriters look for.
How a USDA loan moves from first call to closing
- 1
Pre-qualification call
We ask about income, debts, credit and the area you're shopping in. You'll hear whether USDA is realistic and how it stacks up against other loans.
- 2
Pre-approval and home search
We verify pay stubs, W-2s, tax returns and bank statements, then issue a pre-approval letter. Send us each address before you make an offer so we can confirm eligibility.
- 3
Appraisal and underwriting
The USDA appraisal checks value and confirms the property is safe, sound and sanitary. Problems with the roof, heating, water or septic system may need fixing before closing, and we'll tell you early if the report flags anything.
- 4
USDA review and closing
Once our underwriter approves, USDA reviews the file and issues its commitment. Then we schedule closing and walk you through the final numbers before you sign.
What shapes the cost of a USDA loan
A USDA loan saves you the down payment, but it still carries fees and closing costs. Several factors set your rate and your total cost, and we'll go over each one with you when you call. After you apply, you get an itemized Loan Estimate so you can compare line by line.
- Upfront guarantee fee
- USDA charges a one-time guarantee fee at closing. Most borrowers roll it into the loan amount instead of paying it in cash.
- Annual fee
- A smaller yearly fee is spread into your monthly payment and stays for the life of the loan. It's one reason we compare USDA with a conventional loan before you commit.
- Credit and debts
- Your credit score and debt-to-income ratio affect the rate you're offered and how smoothly the file moves through approval.
- Closing costs and seller help
- Title, appraisal, escrow setup and prepaid taxes and insurance still apply. Texas property taxes make the prepaid escrow a real line item, and sellers can sometimes cover part of these costs.
- When you lock your rate
- Rates move daily. When you lock, and for how long, changes what you pay.
USDA loan questions we hear often
Something not covered here? (512) 456-9507
Is Leander eligible for USDA loans?
Parts of the area are and parts are not, and USDA updates its maps from time to time. The only reliable answer is to check the specific address. Tell us the property or the area you're looking at and we'll look it up during your call.
Can I use a USDA loan for new construction?
Yes. A newly built property can qualify as long as it's in an eligible area, you meet the income rules and it passes the appraisal. We plan around your builder's timeline so the USDA review doesn't hold up closing.
Does the income limit count my parents or a roommate?
It counts every adult who will live there, even if they aren't on the loan. Their income won't help you qualify for the payment, but it does count toward the limit. We sort that out early so underwriting holds no surprises.
How long does a USDA loan take to close?
Usually a bit longer than a conventional loan, because USDA does its own review after our approval. Timing varies with how busy the agency is. We build that into the contract dates you and your agent agree to.
Can I refinance a USDA loan later?
Yes. Existing USDA borrowers can sometimes use a USDA streamlined refinance, and once you've built equity you may refinance into a conventional loan to drop the annual fee. We've been NMLS licensed for 10 years and can run those numbers whenever your situation changes.
Find out if USDA works for the address you want
Tell us where you're shopping and give us a rough picture of your income and savings. We'll check eligibility, walk you through pre-qualification and show how USDA compares with your other options.