About Home Loans Leander: A Mortgage Lender That Explains Every Option
We help borrowers in Leander compare home loans side by side before they commit. You hear how each option handles down payment, rate, mortgage insurance and closing costs, so the loan you pick fits your budget today and the plans you have for the next few years.
How we work with borrowers
Our 11 years in the mortgage industry, and the NMLS license we have held for 10 years, shape how every first conversation goes. Over that stretch we noticed a pattern. The borrowers who regret a loan usually never saw what else was available. They were handed one product, one rate and a reason to hurry.
So we spread the choices out the way a builder sets materials side by side before a project starts. A conventional loan may let you remove mortgage insurance after you build enough equity. An FHA loan is more forgiving on credit scores, though its insurance tends to stay on the loan longer. VA and USDA loans can mean little or nothing down for buyers who qualify. Every option gives something and asks for something, and we tell you plainly what that is.
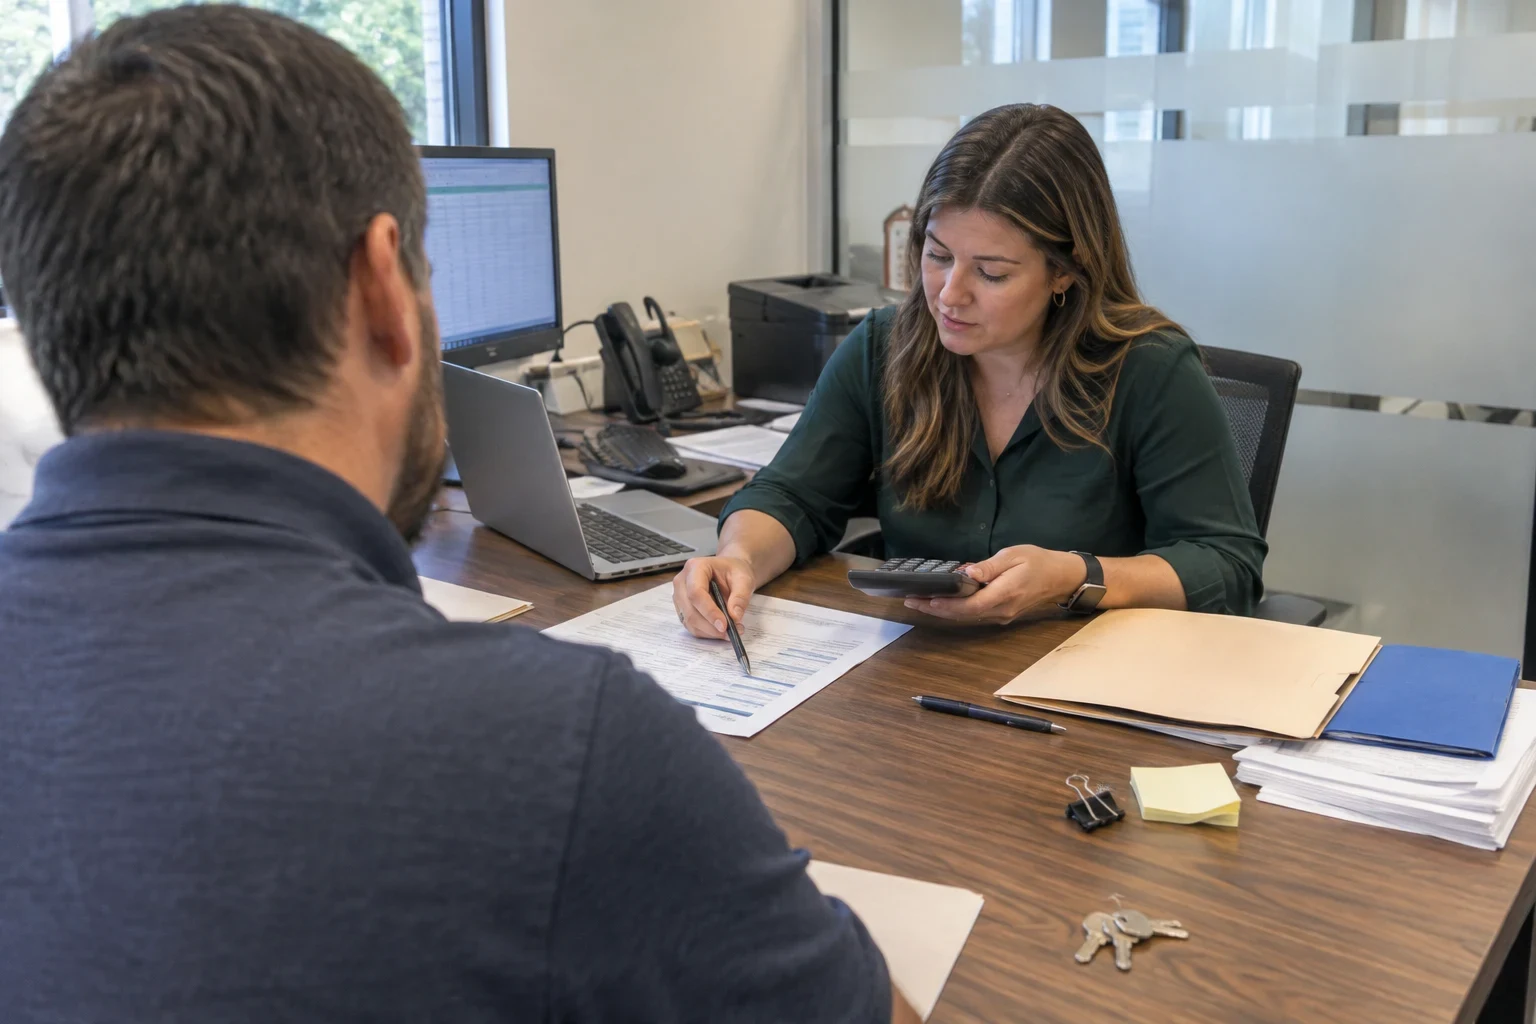
You can meet with us at our office or talk by phone and video, depending on what fits your week. Pre-qualification comes first, so you have a rough idea of how much you can borrow. Once you are ready to make offers, we take a full application and work toward pre-approval. At each stage, you get the numbers in writing.
What you can expect from us
- 01
Side-by-side comparisons
When more than one loan could work, we show them together: monthly payment, cash to close, mortgage insurance, and how each behaves if rates fall and you want to refinance later.
- 02
Straight answers on what you qualify for
If a program is a stretch, we say so early. A self-employed borrower may be a better fit for a bank statement loan than a conventional one, and we explain why before you gather a stack of paperwork.
- 03
Costs explained before closing
Lender fees, title charges, prepaid taxes and insurance all land on your closing statement. We walk through each line well before closing day, so nothing on it catches you off guard.
- 04
Options beyond the first purchase
Owners with equity can look at a HELOC. Investors can weigh hard money loans against bridge loans for short-term financing. The approach stays the same: what it costs, what it asks of you and when it makes sense.
Serving borrowers across the Leander area
We work with buyers, owners and investors in Leander and nearby communities, including Cedar Park, Liberty Hill, Santa Rita Ranch, Round Rock, Georgetown and Pflugerville, along with Brushy Creek, Jonestown, Lago Vista and Hudson Bend. Some properties toward the outer edges of the area may fall inside USDA eligible zones, so we check the specific address before ruling that program in or out.
- Leander
- Cedar Park
- Brushy Creek
- Liberty Hill
- Santa Rita Ranch
- Jonestown
- Round Rock
- Georgetown
- Lago Vista
- Hudson Bend
- Pflugerville
Start with a pre-qualification
A short conversation gives you a realistic borrowing range and a first look at which loan types fit. From there we can move to rate quotes or a full application when you are ready.