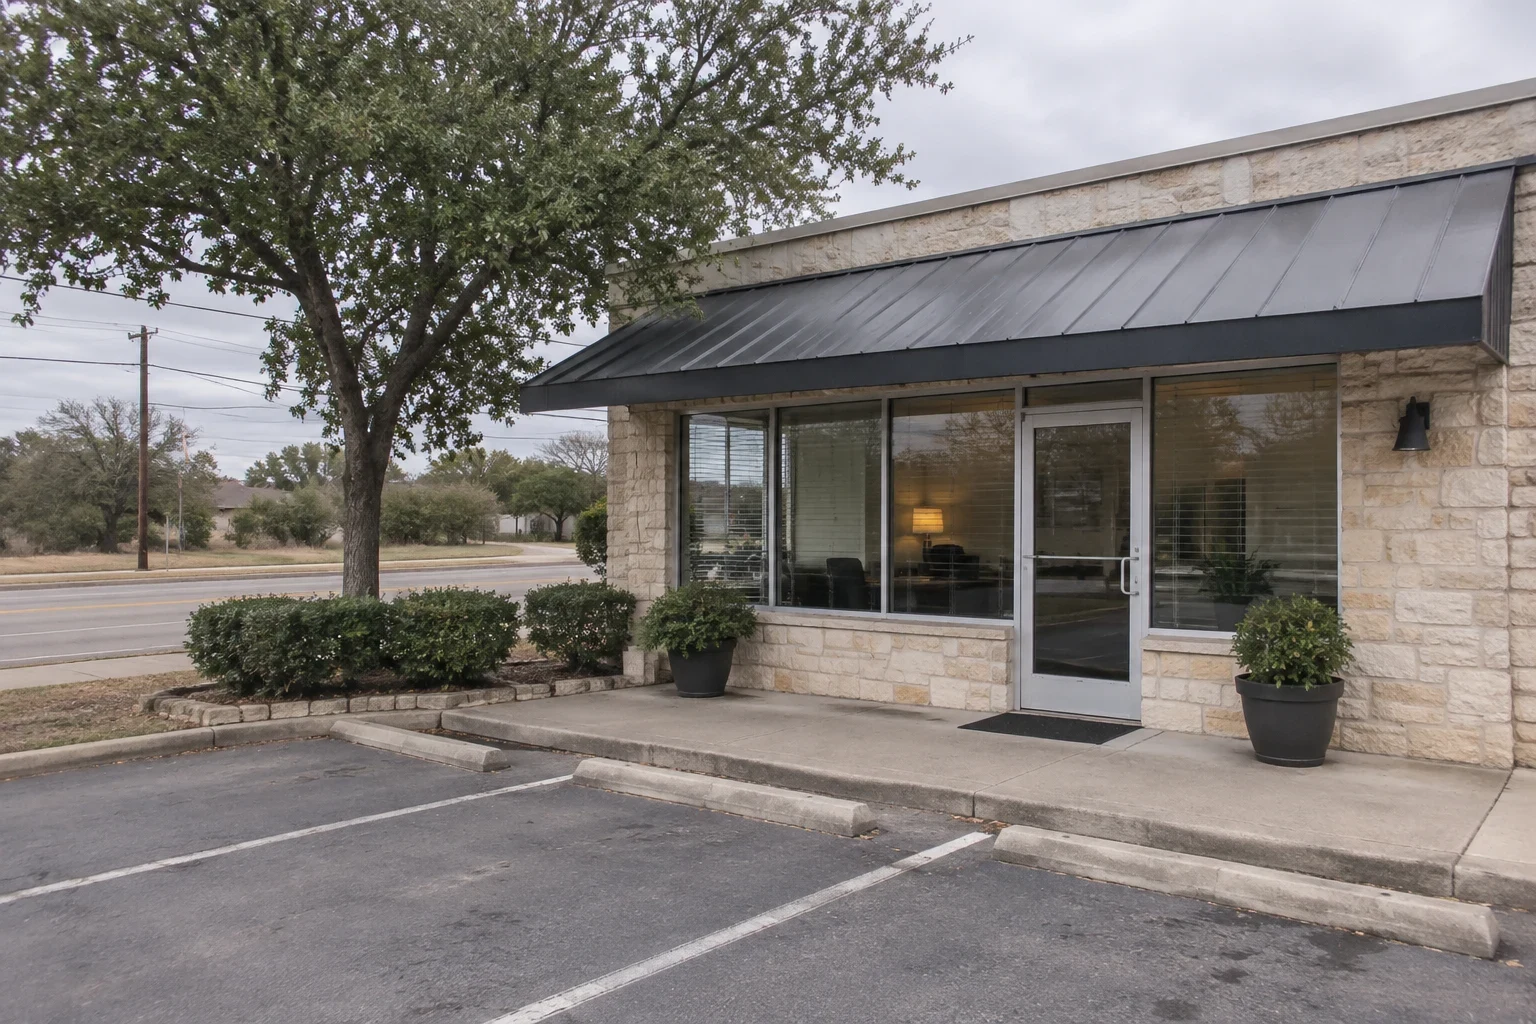
Home Loans in Leander and Nearby Towns
We help borrowers in Leander and the surrounding towns pick the home loan that fits both the property and the plan. We meet at our office or by phone and video, so distance is never a barrier. Every loan type has trade-offs, and we lay them out plainly.
Towns we cover from Leander
- Leander
- Cedar Park
- Brushy Creek
- Liberty Hill
- Santa Rita Ranch
- Jonestown
- Round Rock
- Georgetown
- Lago Vista
- Hudson Bend
- Pflugerville
Not on the list? Call (512) 456-9507 and ask.
Where Our Borrowers Buy and Refinance
Most of our borrowers buy or refinance in Leander, Cedar Park, Brushy Creek and Santa Rita Ranch, but we work just as often with people in Liberty Hill, Georgetown, Round Rock and Pflugerville. A first-time buyer looking at a starter property and an investor picking up a rental can sit at the same table with us and leave with very different plans. That is how it should be. A conventional loan, an FHA loan and a VA loan each ask for different things at closing, and the right choice depends on the property as much as on you.
Out toward the lake, in Lago Vista, Jonestown and Hudson Bend, we see more second homes, larger lots and older properties that need extra attention during appraisal. Self-employed buyers often lean on bank statement loans, and people moving up sometimes need a bridge loan to buy before they sell. When you call, a loan officer starts with your goal, then walks through which options you qualify for and what each one costs over time.
What Shapes a Loan Around Here
- 01
New construction and builder timelines
Much of the area's newer housing comes from active builders. A new build usually takes longer to reach closing than a resale, so we time the rate lock to the builder's schedule and talk through your choices if the completion date moves.
- 02
HOA dues and MUD taxes
Many master-planned neighborhoods across the metro charge HOA dues, and some fall inside municipal utility districts that raise the property tax bill. Both go into the monthly payment we use to figure what you qualify for, so we account for them early instead of finding them at closing.
- 03
Property taxes and the escrow account
With no income tax at the state level, Texas leans on property taxes, and they make up a bigger share of the monthly payment than many buyers expect. Taxes and insurance are usually collected through escrow, and that amount can climb after the first year when the appraisal district updates the value. We show you the full figure before you commit.
- 04
Hail season and insurance
Spring hail is a regular part of Central Texas weather, and insurers price for it. Lenders require hazard coverage before closing, and many local policies carry a percentage-based wind and hail deductible. Getting an insurance quote early keeps the payment estimate honest. Some properties near the lake also need flood coverage.
- 05
Texas rules on borrowing equity
Texas caps borrowing against a primary residence, generally at 80 percent of its value when combined with the first mortgage, and adds its own disclosure and waiting rules. We explain how those limits affect a HELOC before you apply.
Talk Through Your Options Before You Shop
Tell us the town, the type of property and the monthly payment you have in mind. We will go over which loans fit and start your pre-qualification on that first call.